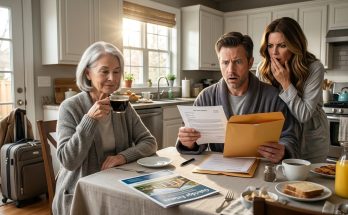
The telephone rang while Mark and Tessa were clearing the dinner dishes on a Wednesday evening. Tessa answered with a dish towel over one shoulder. Within seconds, Mark noticed the change in her expression. She stopped moving, lowered herself into a kitchen chair, and asked her mother to repeat what she had just said.
Diane was three months behind on her mortgage.
She hadn't told anyone about the missed payments. She had ignored earlier correspondence from the mortgage company, hoping she could catch up before the situation became serious. Now she had received a formal letter, and the language frightened her. She told Tessa that the bank was preparing to take her house.
Tessa asked her to read the heading. Diane resisted, accusing her daughter of treating her like a child. Eventually, she admitted that the document was a notice of default. It wasn't an eviction order, and no foreclosure sale had been scheduled for the following morning, but the mortgage was seriously delinquent. Diane needed to respond before her options narrowed.
Mark sat beside Tessa while she asked how much money was overdue. Diane initially avoided giving a figure. When Tessa insisted, her mother admitted that the arrears and associated charges totaled slightly more than fifty-four hundred dollars. Tessa stared at the table. The amount was painfully close to the five thousand dollars she had once borrowed from Linda under false pretenses.
Diane explained that her income hadn't been enough to cover everything. She had refinanced the house years earlier and still carried a substantial mortgage. She had also been helping Kyle, Tessa's younger half-brother, with rent after he lost his job. Several home repairs had gone onto credit cards, and an increase in property taxes had made the monthly budget even tighter.
Tessa recognized the pattern before her mother finished describing it. Diane had used borrowed money to maintain ordinary expenses, continued helping someone else when she couldn't afford to, and concealed the problem until the consequences became difficult to manage. The details were different from Tessa's old financial crisis, but the underlying decisions were disturbingly familiar.
Then Diane asked for six thousand dollars. She said Mark and Tessa were doing well now, and she promised to repay the money once she got everything straightened out. Tessa looked toward Mark. He didn't answer for her. He simply waited, giving her the opportunity to make the decision she had spent years learning how to make.
Tessa explained that they didn't have six thousand dollars available to lend. Diane immediately pointed out that they had savings. Tessa distinguished their emergency fund from money they could comfortably give away. When Diane mentioned their retirement accounts, Tessa said those funds weren't available for solving a problem that had developed over several months.
Her mother's voice hardened. She reminded Tessa of everything she had provided while raising her and asked whether that meant nothing now. Tessa acknowledged the sacrifices without changing her answer. Diane began crying and accused her daughter of caring more about a bank account than her own mother.
The accusation hurt. Tessa had spent much of her life trying to demonstrate affection through money, gifts, and gestures she couldn't always afford. She knew how quickly shame could make a financial decision feel like a test of loyalty. For a moment, she wanted to agree to the loan simply to stop hearing disappointment in Diane's voice.
Instead, she offered another kind of help. She would come over the next morning, examine the notice, and call the mortgage servicer with Diane. They could ask about repayment arrangements, loan modification review, and other ways of addressing the delinquency. Tessa would help gather documents and could cover groceries for the week if that eased the immediate pressure. She would not transfer six thousand dollars into Diane's account.
Diane said Tessa had become cold. Tessa's voice shook as she replied that she loved her mother, but she didn't have to put her own household at risk to prove it. The conversation ended badly. Tessa went into the bathroom, closed the door, and cried while Mark remained in the kitchen.
He didn't immediately congratulate her for holding the boundary. He understood that she was grieving the fact that doing something responsible could still leave someone she loved frightened and angry. When she returned, he asked what she needed. Tessa said she wanted her mother to keep her home. She also admitted that part of her still wanted to send the money.
Mark acknowledged that they could technically withdraw funds and make the transfer. Then he asked what would happen afterward. Their own reserves would be smaller, Diane would still have credit card balances and other obligations, and no one would have addressed the spending pattern that had caused the missed payments. The money might postpone the crisis without resolving it.
Tessa sat quietly for a long time. Then she told Mark she finally understood what Linda had experienced when she borrowed the emergency fund. Mom had wanted to help someone she loved. She had believed a promise that the money would return. Only later had she discovered how much financial security she had surrendered.
The following morning, Tessa arrived at Diane's house with a notebook, a folder, and enough patience to endure several difficult conversations. She asked to see the mortgage notice, recent statements, and information about household income. Diane complained that the process was humiliating. Tessa replied that understanding the numbers was the first step toward making a useful plan.
They called the mortgage servicer together. The representative explained that Diane would need to submit financial documentation and a hardship explanation before certain assistance options could be evaluated. They discussed the possibility of a structured repayment arrangement and review for a modification. Nothing was guaranteed, and the overdue amount wasn't simply going to disappear.
Diane was discouraged. She had hoped Tessa would persuade someone to reduce the balance or obtain an immediate extension. Instead, she was being asked to document her income, expenses, and circumstances. Tessa helped organize the paperwork without pretending the process would be quick or easy.
As they gathered records, more debt emerged. Diane had outstanding credit card balances, a home-improvement loan, and repeated transfers to Kyle. Some payments to her son had been made during months when she was already falling behind on her own mortgage. Diane defended those transfers by explaining that Kyle had been struggling.
Tessa understood the impulse. She also saw that her mother had been using money she needed for housing to support another adult's expenses. The arrangement couldn't continue without putting Diane's home at greater risk.
She encouraged Diane to speak directly with Kyle. The conversation went badly. Kyle insisted that his mother had always helped him and accused Tessa of refusing to contribute now that she had a better job. He suggested that she and Mark should simply pay the mortgage arrears.
Tessa told him the mortgage wasn't hers. Kyle responded that Diane was their mother. Tessa agreed, but she refused to accept that family connection made her responsible for every debt Diane incurred. She could help with paperwork, transportation, and practical expenses without assuming ownership of the mortgage.
Kyle called her selfish. Then he complained that she sounded like Rachel. Tessa almost laughed. She told him not to repeat that comparison to me because I would become impossible to live with. When I heard about the exchange later, I laughed until my stomach hurt.
The situation took months to stabilize. Tessa accompanied Diane to a housing counseling agency that provided foreclosure-prevention assistance. They reviewed the mortgage documents and prepared the information needed for the servicer's evaluation. Diane eventually qualified for a structured repayment arrangement that incorporated part of the overdue amount into scheduled payments.
She also sold a second vehicle she rarely used. The proceeds helped reduce immediate pressure, and eliminating its insurance and maintenance costs improved her monthly budget. Kyle found steadier work and resumed paying his own rent. The changes weren't dramatic, but together they made Diane's finances more manageable.
Tessa contributed two grocery deliveries and paid one utility bill as gifts. She didn't demand repayment or describe the assistance as a loan. She also didn't transfer six thousand dollars. Diane remained resentful for a while, occasionally reminding Tessa that a single payment would have been easier than months of paperwork and telephone calls.
One afternoon, Diane admitted that she had misunderstood her daughter's refusal. She had believed Tessa was unwilling to help. Looking back, she could see that Tessa had spent many hours gathering records, attending appointments, and following up on the mortgage arrangement. Diane said she still would have preferred receiving the money. Tessa acknowledged that without arguing. They laughed, and the tension between them eased.
At our next family dinner, Tessa explained what had happened. Linda listened closely, occasionally asking practical questions about the repayment arrangement and Diane's budget. When Tessa finished, Mom told her she was proud of the way she had handled the situation.
Tessa smiled and said she finally understood why Linda had needed boundaries. Money could solve an immediate problem without addressing the behavior that created it. Refusing a particular request didn't mean refusing to help the person who made it. Sometimes the more useful assistance required time, patience, and uncomfortable honesty.
Howard raised his glass to the family's increasingly unexciting financial wisdom. Mark complained that we had all become unbearably responsible. I told him that he had been unbearable long before he learned to balance a budget. The conversation moved on to dinner, and for once the subject of money ended without anyone feeling injured.
Later, Tessa and I washed dishes together. She mentioned Kyle's accusation that she sounded like me. I offered my condolences. She smiled, then grew quiet. She said she now understood why I had been so angry during our original telephone conversation, when she dismissed Linda's need for five thousand dollars.
I told her I had been angry because Mom was frightened and embarrassed. Tessa said she hadn't seen that. She had thought about the money as a number in an account, something she could borrow and eventually replace. I had seen my mother kneeling beside a broken refrigerator, surrounded by leaking water and food she was trying to save.
Tessa set down the plate she was drying. She apologized for putting Linda in that position and for making me witness her fear. It was the most specific apology she had ever offered me. She didn't ask me to reassure her or declare that everything had been forgiven. She simply acknowledged what she had done.
I thanked her. The words were enough.
A month later, Diane sent Linda a handwritten card. She explained that Tessa had helped her without taking over her finances and said she believed her daughter had learned that distinction from Linda. Mom brought the card to my house, delighted. When I suggested storing it with the old repayment ledger, she shook her head. The ledger recorded what had happened. The card, she said, showed what someone had learned from it.
Mark and Tessa also established a written family lending policy. They agreed never to lend money they couldn't afford to lose. Any loan exceeding two hundred dollars would require a written repayment arrangement, and neither spouse would lend joint funds without the other's agreement. Emergency savings and retirement accounts would remain protected. When a loan wasn't appropriate, they could consider a smaller gift.
The rules seemed excessively formal until Kyle asked Mark privately for nine hundred dollars to repair his car. Mark didn't agree or refuse immediately. He told Kyle he would discuss the request with Tessa because it involved shared money. Kyle mocked him for needing permission, but Mark explained that they had made an agreement about decisions affecting both of them.
After reviewing their budget, Mark and Tessa offered Kyle two hundred dollars as a gift and helped him locate a mechanic willing to arrange payments for the remaining repair cost. Kyle complained about the limited assistance, but he accepted it. His car was repaired, and several weeks later he tried to repay the gift. Tessa returned the money and suggested he keep it for the next repair.
For the first time, their extended family was learning to solve financial problems without quietly transferring one person's emergency into another person's account.
That change would soon influence a different kind of family decision.
As Linda approached seventy-seven, she began thinking seriously about what would happen to her house when she was no longer there to make decisions about it.
Click here to continue reading: PART 14: As My Mother Planned the Future of Her Home, an Unexpected Illness Reminded Us That Clear Boundaries Could Protect Relationships Even After Death
When My Mother’s Refrigerator Failed, I Discovered Her Emergency Savings Were Gone and a Family Secret Was Waiting Behind One Unpaid Promise
Part 13 of 16